
Prescription Drugs Market Size, Share, Trends, Forecast Report 2026 To 2035
Prescription Drugs Market (By Product Type: Generics, Orphan, Other Prescription Drugs; By Therapy: Oncology, Anti-diabetics, Vaccines, Sensory Organs, Immunosuppressants, Anticoagulants, Others; By Distribution Channel: Hospital Pharmacies, Retail Pharmacies & Drug Stores, Online Pharmacies) - Global Industry Analysis, Size, Share, Regional Analysis, Trends and Forecast 2026 - 2035
- Last Updated: 03 Nov 2026
- Report Code: ARC2530
- Category: Healthcare and Pharmaceuticals
Prescription Drugs Market Size, Forecast 2026 To 2035
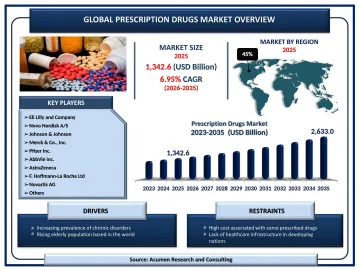
The global prescription drugs market size was valued at $1,342.6 billion in 2025. The market is projected to reach $2,633.0 billion by 2035 from $1,438.2 billion in 2026, expanding at a CAGR of 6.95% during the forecast period. The prescription drugs market is growing on the back of a rising chronic disease burden, a rapidly ageing population, and a strong pipeline of innovative medicines. Surging demand for GLP-1 based diabetes drugs and anti-obesity drugs, wider use of monoclonal antibodies in oncology and immunology, and broader access to affordable generics and biosimilars are expanding prescription volumes and spending worldwide.
- Base Year Market Size (2025): $1,342.6 billion
- Current Year Market Size (2026): $1,438.2 billion
- Estimated Year Market Size (2035): $2,633.0 billion
- Forecast Period CAGR (2026-2035): 6.95%
Report Highlights
- By region: North America dominated the prescription drugs market with a 45.0% share in 2025, generating USD 604.2 billion in revenue. Asia-Pacific is the fastest-growing region, with a projected CAGR of 8.3% from 2026 to 2035, and is expected to reach USD 658.2 billion by 2035.
- By product type: Other prescription drugs (branded and patented medicines) dominated the product type segment with a 64.0% share in 2025, generating USD 859.3 billion in revenue. Orphan drugs are projected to grow at the fastest rate, with a CAGR of 10.9% from 2026 to 2035.
- By therapy: Oncology dominated the therapy segment with a 21.0% share in 2025, generating USD 281.9 billion in revenue. Anti-diabetics, including GLP-1 based diabetes and obesity medicines, are projected to grow at the fastest rate, with a CAGR of 10.2% from 2026 to 2035.
- By distribution channel: Retail pharmacies & drug stores dominated the distribution channel segment with a 48.0% share in 2025, generating USD 644.4 billion in revenue. Online pharmacies are projected to grow at the fastest rate, with a CAGR of 10.8% from 2026 to 2035, raising their share from 14.0% in 2025 to 20.0% by 2035.
What Is the Prescription Drugs Market?
The prescription drugs market covers medicines that can be dispensed only against a valid prescription from a licensed healthcare professional, because their safe and effective use requires medical supervision. It includes branded (patented) innovator medicines, generic drugs, biologics and biosimilars, and orphan drugs for rare diseases, used across therapy areas such as oncology, diabetes, immunology, infectious diseases and cardiovascular disorders, and dispensed through hospital pharmacies, retail pharmacies and drug stores, and online pharmacies.
Recent Trends
- Shift from injectable to oral GLP-1 medicines: The approval of once-daily GLP-1 pills for weight management in the U.S. is widening patient access to obesity and diabetes treatment beyond injectables.
- Government drug price negotiation: Medicare-negotiated prices for selected high-spend medicines took effect in the U.S. in January 2026, reshaping pricing and launch strategies for branded drugs.
- Rising biosimilar and generic uptake: Patent expiries for several blockbuster brands before 2030 are opening space for lower-cost alternatives and expanding treated patient populations.
- Subcutaneous and patient-friendly formulations: Drugmakers are converting intravenous biologics into subcutaneous versions to shorten administration time and ease the load on infusion centres.
- Digital prescribing and e-pharmacy growth: E-prescriptions, telehealth consultations and direct-to-patient programs are moving a growing share of prescriptions to online channels.
Investment Outlook: Where Will Capital Flow Through 2035?
- Eli Lilly announced plans in February 2025 to build four new U.S. manufacturing sites, more than doubling its U.S. manufacturing investment commitments since 2020 to over $50 billion.
- Johnson & Johnson announced in March 2025 that it will invest more than $55 billion in U.S. manufacturing, research and development, and technology over four years.
- Roche announced in April 2025 a $50 billion investment in U.S. pharmaceutical and diagnostics manufacturing and research over five years.
- Novartis announced in April 2025 plans to invest $23 billion in U.S. manufacturing and R&D infrastructure over five years.
- AstraZeneca announced in July 2025 a $50 billion investment in U.S. manufacturing and research by 2030.
Regulatory and Quality Landscape
| Country / region | Regulatory authority | Key regulatory framework |
|---|---|---|
| United States | Food and Drug Administration (FDA) | Federal Food, Drug, and Cosmetic Act (FDCA); prescription drug advertising rules under 21 CFR Part 202; cGMP under 21 CFR Parts 210 and 211; Medicare drug price negotiation under the Inflation Reduction Act |
| European Union | European Medicines Agency (EMA) and national competent authorities | Directive 2001/83/EC on medicinal products for human use, Regulation (EC) No 726/2004, and EU GMP guidelines (EudraLex Volume 4) |
| United Kingdom | Medicines and Healthcare products Regulatory Agency (MHRA) | Human Medicines Regulations 2012 and UK GMP requirements |
| Japan | Pharmaceuticals and Medical Devices Agency (PMDA) and Ministry of Health, Labour and Welfare (MHLW) | Pharmaceuticals and Medical Devices Act and National Health Insurance drug price listing |
| China | National Medical Products Administration (NMPA) | Drug Administration Law and National Reimbursement Drug List (NRDL) negotiations |
| India | Central Drugs Standard Control Organisation (CDSCO) and State Licensing Authorities | Drugs and Cosmetics Act and Rules, Schedule H prescription drug rules, Revised Schedule M GMP, and New Drugs and Clinical Trials Rules, 2019 |
Prescription Drugs Market Dynamics
Growth Drivers
- Rising Chronic Disease Burden: Cancer alone accounted for approximately 20 million new cases and 9.7 million deaths in 2022, according to the WHO's International Agency for Research on Cancer, while diabetes affects close to 589 million adults, as per the International Diabetes Federation's 2025 Diabetes Atlas. Long-term disease management is lifting prescription volumes in every major region.
- Ageing Global Population: The WHO projects that one in six people worldwide will be aged 60 or over by 2030. Older patients typically manage several chronic conditions at once and use more medicines per capita, steadily increasing demand.
- Strong Innovation Pipeline: New launches in GLP-1 metabolic drugs, antibody-drug conjugates, bispecific antibodies, and cell and gene therapies are adding high-value revenue streams and expanding treatment options for previously underserved conditions.
Restraints
- Drug Pricing Reforms: Government price negotiation, reference pricing and reimbursement controls in major markets are moderating price growth for established branded medicines.
- Patent Expiries: Several blockbuster brands face loss of exclusivity before 2030, shifting revenue from originators to lower-priced generics and biosimilars.
- High Cost of Specialty Medicines: Premium prices for biologics, gene therapies and orphan drugs limit access for many patients, particularly in low- and middle-income countries with limited insurance coverage.
Opportunities
- Orphan and Rare Disease Therapies: Regulatory incentives, premium pricing and advances in gene and cell therapy are accelerating development of treatments for rare diseases, the fastest-growing product type.
- Biosimilar Expansion: Upcoming patent expiries for major biologics create opportunities for biosimilar developers and for payers seeking to lower treatment costs.
- Emerging Market Access: Expanding health insurance coverage and rising healthcare spending across Asia-Pacific, Latin America and the Middle East are opening large new patient populations.
Challenges
- Supply Chain Resilience: Dependence on concentrated sources of active pharmaceutical ingredients and tariff uncertainty are pushing companies to reshore and diversify manufacturing.
- Rising R&D Costs and Attrition: Developing a new medicine remains costly and lengthy, with many candidates failing in late-stage clinical trials.
- Counterfeit and Unregulated Online Sales: Growth of online channels raises the risk of falsified medicines, requiring strong verification, licensing and enforcement.
Prescription Drugs Market Segmental Insights
Product Type Insights
Other Prescription Drugs (Branded and Patented): Other prescription drugs dominated the product type segment with a 64.0% share in 2025, valued at USD 859.3 billion. Demand is driven by high-value innovator medicines and biologics in oncology, immunology and metabolic disease, along with steady new product launches.
Generics: Generics accounted for 27.0% of the market in 2025, valued at USD 362.5 billion, ranking second. Generics make up the large majority of prescriptions dispensed by volume and remain central to affordability programs run by governments and payers.
Prescription Drugs Market Share, By Product Type, 2025 & 2035 (%)
| Product Type | Revenue Share, 2025 (%) | Revenue Share, 2035 (%) |
|---|---|---|
| Other Prescription Drugs | 64% | 60% |
| Generics | 27% | 27% |
| Orphan | 9% | 13% |
Orphan Drugs: Orphan drugs represented 9.0% of the market in 2025, valued at USD 120.8 billion, and are projected to grow at the fastest CAGR of 10.9% from 2026 to 2035, supported by regulatory incentives and advances in gene and cell therapies for rare diseases.
Therapy Insights
Oncology: Oncology dominated the therapy segment with a 21.0% share in 2025, valued at USD 281.9 billion. Demand is driven by immune checkpoint inhibitors, targeted therapies and antibody-drug conjugates moving into earlier lines of treatment, along with growing use of cancer immunotherapy.
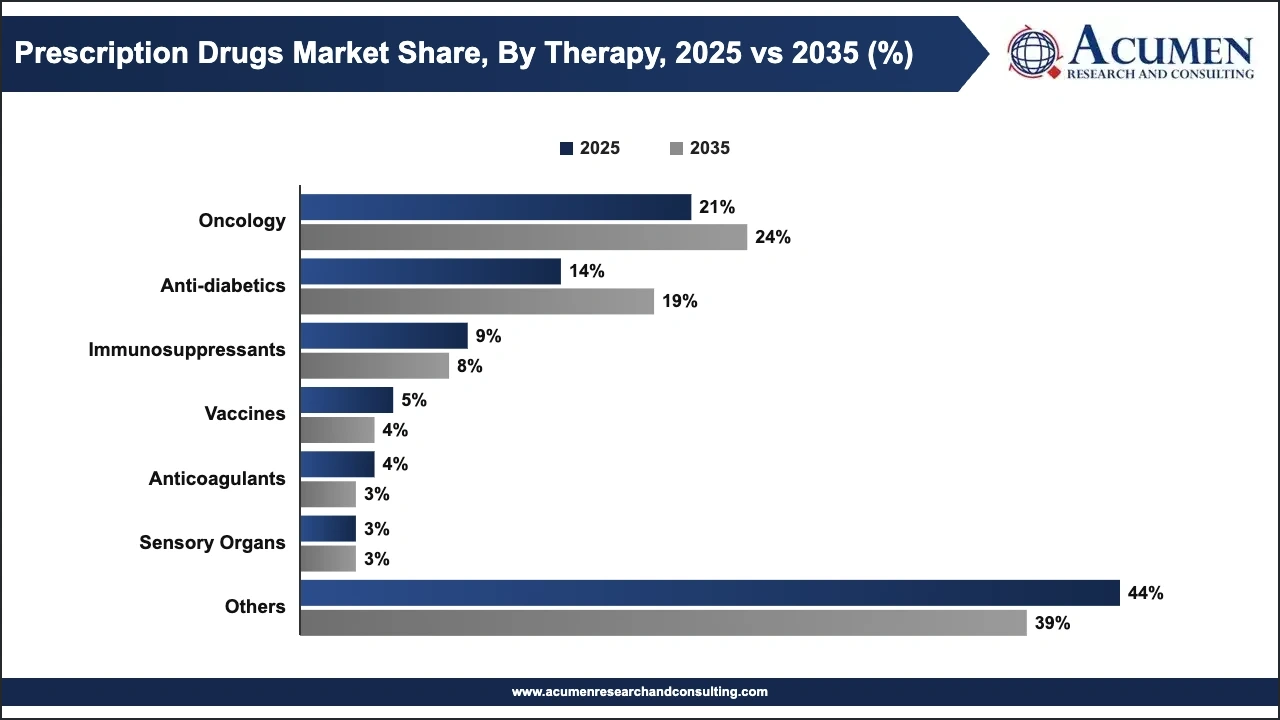
Anti-diabetics: Anti-diabetics accounted for 14.0% of the market in 2025, valued at USD 188.0 billion, ranking second. The segment, which includes GLP-1 receptor agonists for type 2 diabetes and obesity, is projected to grow at the fastest CAGR of 10.2% from 2026 to 2035, raising its share to 19.0% by 2035 as oral formulations and broader reimbursement reach more patients.
Immunosuppressants: Immunosuppressants represented 9.0% of the market in 2025, valued at USD 120.8 billion, ranking third. Demand is supported by biologic and small-molecule therapies for autoimmune diseases and organ transplantation. Vaccines (5.0%), anticoagulants (4.0%) and sensory organ drugs (3.0%) made up the rest of the named therapy areas in 2025.
Distribution Channel Insights
Retail Pharmacies & Drug Stores: Retail pharmacies and drug stores dominated the distribution channel segment with a 48.0% share in 2025, valued at USD 644.4 billion. They dispense the bulk of chronic-care prescriptions for conditions such as diabetes, hypertension and cardiovascular disease.
Prescription Drugs Market Share, By Distribution Channel, 2025 & 2035 (%)
| Distribution Channel | Revenue Share, 2025 (%) | Revenue Share, 2035 (%) |
|---|---|---|
| Retail Pharmacies & Drug Stores | 48% | 45% |
| Hospital Pharmacies | 38% | 35% |
| Online Pharmacies | 14% | 20% |
Hospital Pharmacies: Hospital pharmacies accounted for 38.0% of the market in 2025, valued at USD 510.2 billion, ranking second. Demand is driven by high-value specialty, oncology and infused biologic therapies administered in inpatient and outpatient hospital settings.
Online Pharmacies: Online pharmacies represented 14.0% of the market in 2025, valued at USD 188.0 billion, and are projected to grow at the fastest CAGR of 10.8% from 2026 to 2035, supported by e-prescriptions, home delivery and manufacturer direct-to-patient programs.
Prescription Drugs Market Regional Insights
Which Region Dominates the Prescription Drugs Market?
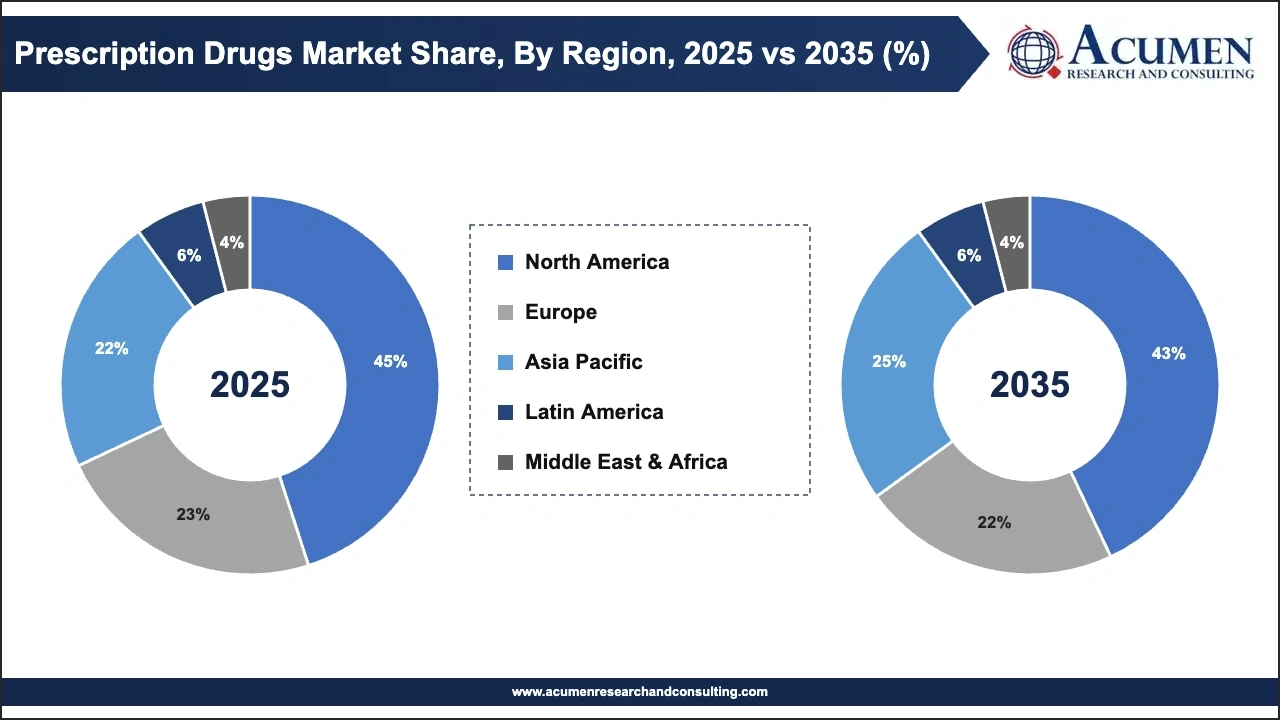
North America held the largest market share of 45% in the prescription drugs market in 2025 and was valued at $604.2 billion in terms of revenue. The region leads owing to high per-capita drug spending, rapid adoption of new branded therapies, a dense pipeline of FDA approvals, broad insurance coverage, and strong uptake of GLP-1, oncology and specialty biologic medicines.
- The U.S. is the key contributor as the world's largest market for prescription medicines. Medicare price negotiation is moderating prices for selected high-spend drugs, while large new investments in domestic manufacturing are strengthening supply.
Which Region Is the Fastest-Growing in the Prescription Drugs Market?
Asia-Pacific is projected to be the fastest-growing regional market, with a CAGR of 8.3% from 2026 to 2035. The region accounted for 22.0% of the global market in 2025, generating USD 295.4 billion in revenue, and is projected to reach USD 658.2 billion by 2035. Growth is supported by expanding insurance coverage, rising chronic disease prevalence, growing healthcare spending and a fast-developing domestic pharmaceutical industry.
China, Japan, India, South Korea and Australia are the main contributors. China is fast becoming a global hub for novel drug innovation and out-licensing, Japan's ageing population sustains high per-capita medicine use, and India's large generics manufacturing base supplies affordable medicines to markets worldwide.
Top Countries & Their Market Shifts
- United States: The largest prescription drugs market, where GLP-1 therapies, oncology and specialty biologics drive spending growth while Medicare price negotiation and expanding biosimilar use moderate prices for mature brands.
- China: Rapid growth in innovative drug development and licensing deals, supported by regulatory reforms and National Reimbursement Drug List negotiations that widen patient access to new medicines.
- Germany: Europe's largest pharmaceutical market, with early access to new medicines through its benefit assessment system and strong uptake of biosimilars.
- Japan: A mature market where an ageing population supports demand, while regular drug price revisions push greater use of generics.
- India: A global leader in generic drug manufacturing with growing domestic demand, expanding health insurance coverage and a rising focus on specialty and biosimilar production.
Top Company
- Eli Lilly and Company (United States)
- Novo Nordisk A/S (Denmark)
- Johnson & Johnson (United States)
- Merck & Co., Inc. (United States)
- Pfizer Inc. (United States)
- AbbVie Inc. (United States)
- AstraZeneca (United Kingdom)
- F. Hoffmann-La Roche Ltd (Switzerland)
- Novartis AG (Switzerland)
- Sanofi (France)
- Bristol Myers Squibb (United States)
- GSK plc (United Kingdom)
Recent Breakthroughs
- April 2026: FDA approves Eli Lilly's oral GLP-1 pill. The U.S. FDA approved Foundayo (orforglipron), a once-daily small-molecule GLP-1 medicine for chronic weight management, after a review of about 50 days under its Commissioner's National Priority Voucher program.
- January 2026: First Medicare-negotiated drug prices take effect. Negotiated prices for the first 10 selected prescription drugs became effective in the United States under the Inflation Reduction Act.
- December 2025: FDA approves the Wegovy pill. Novo Nordisk received U.S. FDA approval for oral semaglutide (Wegovy pill), the first oral GLP-1 medicine for chronic weight management, with launch in early January 2026.
- September 2025: FDA approves subcutaneous Keytruda. Merck received U.S. FDA approval for Keytruda Qlex, a subcutaneous formulation of pembrolizumab for solid tumors, offering faster administration than the intravenous version.
Segments Covered
By Product Type
- Generics
- Orphan
- Other Prescription Drugs
By Therapy
- Oncology
- Anti-diabetics
- Vaccines
- Sensory Organs
- Immunosuppressants
- Anticoagulants
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies & Drug Stores
- Online Pharmacies
By Region
- North America (U.S., Canada)
- Europe (U.K., Germany, France, Spain, Rest of Europe)
- Asia-Pacific (China, Japan, India, Australia, South Korea, Rest of Asia-Pacific)
- Latin America (Brazil, Mexico, Rest of Latin America)
- Middle East & Africa (GCC, South Africa, Rest of Middle East & Africa)
Looking for discounts, bulk pricing, or custom solutions? Contact us today at sales@acumenresearchandconsulting.com
Frequently Asked Questions
Related Market Research Reports
May 2024
September 2023
September 2023
September 2023
September 2023
April 2023
April 2023
April 2023